How Do I Buy an Existing Business?
To buy an existing business, define your income goals, skills and lifestyle; get your financing lined up; search both listed and off-market opportunities; then make an offer with a Letter of Intent, complete due diligence and close. Buying an established company with proven cash flow is usually faster and less risky than starting from scratch, and lenders will finance it because the cash flow already exists. An experienced Intermediary Advisor helps you avoid costly mistakes at every step.
For corporate professionals and executives ready to stop making someone else’s dreams come true and start owning their income.
Why do so many executives buy an existing business instead of starting one?
Many prospective business buyers come from corporate careers. They already know how to lead teams, manage budgets and hit targets. What they want is to apply those skills to something they own, without spending years building a startup from zero.
An existing business gives you a head start that a startup cannot:
- Proven cash flow from day one, so the business can pay you and service its debt.
- Established customers, suppliers and reputation that took the previous owner years to build.
- Trained employees and working systems, so you lead and grow instead of inventing everything.
- Financing that follows the cash flow. Lenders, including SBA lenders, finance acquisitions because there is a track record to underwrite. That is much harder to get for a startup.
Put simply: buying an established business with proven cash flow is usually easier and more affordable than starting from scratch.
What are the steps to buying a small business?
Every deal is different, but most successful acquisitions follow the same path. Here is the roadmap we walk buyers through:
- Define your target.Map what you love, your skill sets, the schedule you want and the income you need. This becomes your acquisition criteria: industry, size, location and owner role.
- Get financially prepared.Review your liquid capital, credit and retirement assets, and talk with an SBA lender early so you know your buying range before you fall in love with a business.
- Build your team.An Intermediary Advisor, an acquisition-savvy attorney and a CPA. Assemble them before you need them.
- Search listed and off-market opportunities.Review marketplace listings and broker inventory, and pursue off-market owners who are open to selling but have not advertised.
- Screen and evaluate.Sign NDAs, review the offering package, meet the owner and test the numbers: cash flow, trends, customer mix and why the owner is selling.
- Submit a Letter of Intent (LOI).Propose price, structure, financing, transition support and a due diligence period. A well-built LOI protects you and signals you are a serious buyer.
- Complete due diligence and financing.Verify financials, contracts, employees, leases and legal matters while your lender underwrites the loan.
- Close and transition.Sign the purchase agreement, fund the deal and work alongside the seller during an agreed transition so customers and employees stay with you.
Can buying a business replace my corporate salary?
For executives earning $200K–$400K, this is often the real question. The answer depends on one number more than any other: the cash flow the business produces after it pays its debt.
When you buy a business, your personal income comes from the owner’s cash flow (often called Seller’s Discretionary Earnings, or SDE). From that cash flow you pay the acquisition loan, reinvest in the business and pay yourself. If what remains meets or beats your current salary, the business can replace your paycheck while you also build equity you own.
With SBA financing, buyers can put down as little as 5% with loan terms of 10–25 years. In the example published on ess-business.com, a buyer with $25,000 could purchase a $500,000 business netting about $125K per year after debt service.
Illustrative example only. Actual down payment, terms and income depend on the business, the lender and your qualifications.
The same logic scales. To replace a larger salary, you target a business whose cash flow, after debt service and reinvestment, supports the income you need. Unlike a salary, that income comes with three things a corporate job never gives you:
Income you control
Your earnings grow when the business grows, not when a compensation committee approves a raise.
Equity you build
Every loan payment increases your ownership in an asset you can grow, sell or pass on.
Freedom you choose
No more layoffs, reorganizations or someone else deciding your future.
How involved will I need to be after I buy a business?
That depends on the business you choose, which is why defining your role belongs in Step 1. Broadly, businesses fall into three groups:
- Owner-operator businesses, where the owner works in the business daily. These usually offer the most cash flow relative to price, and your management experience transfers quickly.
- Businesses with management in place, where a general manager or key staff run daily operations and the owner leads strategy, finance and growth. These usually cost more relative to cash flow.
- Add-on acquisitions, where an existing owner buys a complementary business to grow faster.
Most executives find their biggest shift is moving from managing a department to being responsible for everything: sales, cash, people and customers. The upside is that every good decision you make now benefits you directly.
What mistakes do first-time business buyers make?
- Shopping without criteria. Chasing every listing wastes months. Define your target first.
- Skipping financing prep. Finding the right business before you know your buying range costs you deals.
- Trusting the asking price. Asking prices are a starting point. Value is supported by verified cash flow.
- Weak Letters of Intent. Vague LOIs lead to renegotiation, delays and broken deals.
- Thin due diligence. Verify the numbers, contracts, customers and employees before you close.
- Underestimating the transition. Plan the seller’s training and introductions to customers and staff.
Each of these is avoidable with a clear process and an experienced advisor on your side of the table.
How does ESS help executives buy a business?
You bring the leadership experience. We bring the acquisition process. As your trusted Intermediary Advisor, ESS guides you through finding, negotiating and closing, so the business you buy pays you.
Identify the right business
We map what you love, your skill sets, the schedule you want and your income goals, then brainstorm industries where your corporate experience gives you an edge.
Find listed and off-market deals
We search active listings and tap off-market opportunities through our intermediary network, so you see businesses many buyers never hear about.
Value the opportunity
As a Certified Valuation Analyst, Jason helps you test the seller's numbers, normalize cash flow and judge whether the price is supported.
Structure the funding
We connect you with SBA lenders and help you blend bank debt, seller financing and your own capital, with the focus where lenders put it: cash flow.
Negotiate the LOI and terms
Jason is a Certified Master Negotiation Expert. He helps you craft the Letter of Intent and negotiate price, terms and transition support.
Manage diligence through closing
We help you assemble your team of attorneys and accountants, organize due diligence and keep the deal moving to the closing table.
Every consultation includes our free Buyers Guide to Successful Acquisitions.
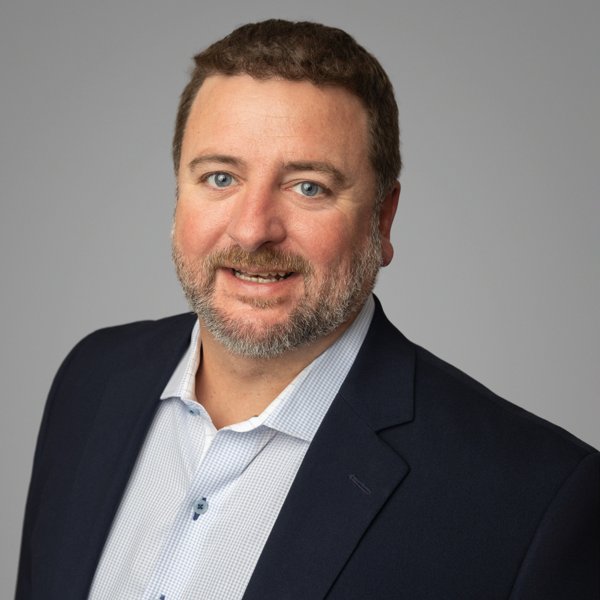
DBA · CVA · CMAP
Why do buyers trust Dr. Jason J. Hubler?
You work directly with Dr. Jason J. Hubler, a Business Intermediary and M&A Advisor who has helped buyers and sellers in Main Street and lower middle-market transactions since 2013.
Jason’s path to business ownership was not handed to him. He was born and raised in York County, Pennsylvania, grew up blue-collar and was the first in his family to graduate college. He lost everything in 2008 and rebuilt. When Covid shut his business down in 2020, he rebuilt again, and 2023 became his best year ever. He knows what it takes to bet on yourself, and he brings that understanding to every buyer he advises.
- Doctorate of Business Administration (DBA), Leadership Studies
- Certified Valuation Analyst (CVA)
- Certified Value Builder (CVB)
- Certified Master Negotiation Expert (CMNE)
- Certified Merger & Acquisition Professional (CMAP)
- Business Intermediary & M&A Advisor, Main Street and lower middle market, since 2013
- 25+ years in sales and entrepreneurial ventures
- President, Pennsylvania Business Brokers Association
- Member: IBBA, NACVA and M&A Source
- 120+ businesses sold
“…I am laser focused on helping buyers buy small main street and lower-middle market businesses, helping buyers overcome their challenges and fears…”
— Dr. Jason J. Hubler
Based in York, Pennsylvania. Serving buyers nationwide, 100% confidential.
From buyer to multi-business owner
Kevin L. of Sparkle Wash in York, PA worked with Jason to buy a business with six-figure cash flow. With that first acquisition established, he went on to buy a second, complementary service business.
“Jason guided the whole process.”
Kevin L., Sparkle Wash, York, PA
Questions executives ask about buying a business
How do I buy an existing business for the first time?
Start by defining your criteria: industry, size, location, the income you need and how involved you want to be. Get pre-qualified with a lender, build a team that includes an Intermediary Advisor, attorney and CPA, then search listed and off-market businesses. When you find the right one, submit a Letter of Intent, complete due diligence and close.
Is it better to buy a business or start one?
For most corporate professionals, buying an established business with proven cash flow is easier and more affordable than starting from scratch. You inherit customers, employees and systems, and lenders can finance the purchase because the cash flow already exists.
Can buying a business replace my corporate salary?
It can, if the business produces enough cash flow after debt service and reinvestment to cover the income you need. In an example published by ESS, a buyer using SBA financing with $25,000 down could buy a $500,000 business netting about $125,000 a year after debt service. Results vary by business, lender and buyer.
How long does it take to buy a business?
Timelines vary widely. The search is usually the longest phase. Once you sign a Letter of Intent, due diligence, financing and closing follow a defined schedule set in the LOI and purchase agreement.
Do I need industry experience to buy a business?
Not always. Lenders and sellers look closely at your management and leadership experience, and many skills from a corporate career transfer directly. Choosing a business with trained staff and a solid seller transition plan reduces the learning curve.
Why should I use a business broker or Intermediary Advisor as a buyer?
An experienced advisor gives you access to listed and off-market opportunities, helps you evaluate value and structure financing, negotiates the Letter of Intent and terms, and keeps due diligence and closing on track, helping you avoid costly mistakes.
Ready to go from executive to owner?
Schedule a confidential call with Dr. Jason J. Hubler. We will talk through your goals, your buying range and the businesses that fit, and you will receive our free Buyers Guide to Successful Acquisitions.